
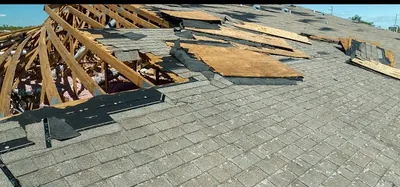
Hail damage you cannot see from the ground
Hail rarely announces itself by putting a hole in your ceiling. It bruises the mat under the granules, and the roof keeps working for another year or two while the damaged areas fail early. By the time a leak shows up, two things have often happened: the policy reporting window has closed, and the storm date is hard to prove.
That is the entire reason to have a roof looked at after a storm you can remember rather than after a leak you cannot ignore.
What we look for
- Hail bruising — soft dark spots where granules are displaced and the mat is fractured
- Wind damage — creased, lifted or missing shingles, and unsealed courses along rakes and ridges
- Flashing displacement at chimneys, walls and skylights
- Collateral evidence on soft metals — gutters, downspouts, vents, screens and AC fins, which date and corroborate the event
- Interior evidence — attic staining and wet insulation
What we do about it
- Free inspection, every slope photographed and documented
- Written scope and measurements you can hand your carrier
- We meet the adjuster at the property and walk the roof with them
- Emergency tarping first if water is entering the building
- Repair or full replacement, permits pulled, cleanup included
Be careful right after a storm
Every hail event brings out-of-state crews with magnetic door signs. Before you sign anything: check licensing and insurance in your jurisdiction, refuse to assign your claim to a contractor, never pay a large deposit up front, and be extremely wary of anyone offering to waive or absorb your deductible — in many states that is insurance fraud, and it implicates you.
What hail actually does to a roof
A hailstone hitting an asphalt shingle does two things at once. It knocks loose the granules — the crushed mineral surface that shields the asphalt underneath from ultraviolet light — and it fractures the fiberglass mat at the point of impact. The second one is the problem. A bruised shingle has a soft, spongy spot you can feel with a thumb but frequently cannot see from a ladder, let alone from the driveway.
That bruise does not leak today. It leaks in two or three years, after the exposed asphalt has baked through a couple of summers, gone brittle, and finally split. By then the storm is long forgotten, the claim window has closed, and what would have been a covered loss is now a homeowner expense. This is the single most misunderstood thing about hail: the damage is real on the day of the storm, but it does not announce itself until the coverage is gone.
Granule loss tells the same story more visibly. If your gutters and downspout splash blocks have a sandy black grit in them after a storm, that grit is your shingle surface. Shingles shed some granules normally as they age. A sudden pile of them after a hail event is different, and it is worth having someone look.
Hail size, and what it usually means
Storm reports describe hail by comparison to everyday objects. Roughly, those translate to:
- Pea — about ¼" · rarely damages a sound asphalt roof, but can mark soft metals
- Dime to nickel — ¾" · damaging to aged, brittle or already-worn shingles
- Quarter — 1" · commonly the size where carriers and manufacturers start expecting functional damage to asphalt shingles
- Golf ball — 1¾" · widespread bruising, granule loss, damage to vents, gutters and siding
- Baseball — 2¾" and up · fractures shingles outright, dents metal roofing, cracks skylights and can breach decking
Size is only part of it. Wind driving the hail sideways changes which slopes get hit and how hard. Hail falling on a twelve-year-old roof does far more than the same stone falling on a two-year-old one. And a roof that has already been through a previous storm has less life left to lose. Two houses on the same street can come out of one storm with genuinely different outcomes.
Wind damage looks nothing like hail damage
Wind works on the seal strip — the adhesive band that bonds each shingle to the one below it. Gusts get under the leading edge, break that bond, and lift the shingle. Often the shingle drops back down looking untouched, but the seal is broken and there is now a crease across it. The next storm pushes water straight underneath. A creased shingle is failed even though it is still sitting where it belongs.
Wind damage concentrates where the roof gives it an edge to grab: ridges and hip lines, rakes and eaves, and anywhere a slope changes direction. Ridge caps usually go first. Missing shingles are the obvious version, but they are a minority of real wind claims — most of it is lifted, creased and unsealed material that looks fine from the ground and fails quietly.
A roof is more than shingles
When a storm damages a roof, the shingles are just the visible layer. A real inspection covers the whole system:
- Underlayment — the water barrier beneath the shingles, and the last defense once they are compromised
- Flashing — chimneys, walls, dormers and skylights, where most storm-related leaks actually begin
- Valleys — where two slopes dump their combined water, and where hail impacts concentrate
- Pipe boots — rubber collars around plumbing vents that crack and leak long before the shingles do
- Ridge vents and turbines — frequently dented, unseated or pulled loose by wind
- Decking — the wood beneath it all; saturated or delaminated decking will not hold a new roof
- Gutters, downspouts and drip edge — dented, detached or pitched wrong after a storm, sending water into the fascia
- Ventilation — a roof that cannot breathe cooks shingles from underneath and shortens every warranty on the house
The evidence that is not on the roof
Adjusters rarely decide a hail claim on the shingles alone. They look for collateral damage on softer surfaces, because those record the storm more clearly and help establish when it happened: dents in gutters and downspouts, bruising on fascia and drip edge, bent fins on the air conditioner, dinged window wraps and screens, marks on the mailbox, the grill lid, the deck boards and the garage door.
This matters for a practical reason. If a carrier is deciding whether damage on your roof came from this storm or an older one, soft metals are a good part of the argument. It is also why we photograph the whole property, not just the slopes — and why we do that before anything gets tarped or cleaned up.
What storm damage does inside the house
Water that gets past a roof rarely lands directly below the opening. It follows the decking, runs along a rafter, crosses the attic and shows up somewhere unrelated — which is why a ceiling stain in one room can come from a failure on the far side of the house. By the time a stain is visible on drywall, water has typically been moving through the structure for a while.
In an attic, look for damp or matted insulation, dark streaking on the underside of the decking, daylight at penetrations and rusted nail tips. Wet insulation loses most of its R-value and does not recover, so an unnoticed leak raises heating and cooling bills long before it causes visible damage. Given warmth and moisture, microbial growth can begin within a couple of days — one more reason the first call after a storm matters more than the second.
Why waiting is the expensive choice
Insurance policies set their own reporting deadlines for storm claims, and they are frequently shorter than homeowners assume. Because hail damage hides, roofs regularly get inspected for the first time well after the window has shut. At that point the conversation is no longer about coverage — it is about what a full replacement costs out of pocket.
There is a second clock too. Most policies cover the storm damage but exclude what happens because you left it. A bruised shingle that splits and lets water into the decking for eighteen months creates rot a carrier can reasonably decline to pay for. Documenting the damage early protects the claim even if the repair itself is scheduled later.
How a storm-damage insurance claim actually works
We are a roofing contractor, not an insurance company or a public adjuster. What we do is document what the storm did and make sure nothing gets missed. The process usually runs like this:
- Free inspection. We walk the roof slope by slope, chalk and photograph impacts, check soft metals and collateral surfaces, and look in the attic where access allows.
- You get the documentation. Photographs and findings, in plain language, whether or not there is enough damage to file. Sometimes the honest answer is that your roof is fine.
- You file the claim. It is your policy and your call — the claim has to come from you.
- The adjuster inspects. We meet them on site whenever we can, so the same evidence is in front of both parties at the same time.
- Scope and pricing get agreed. If line items are missing — ventilation, flashing, code-required items, steep or multi-story access — that is handled as a supplement, with documentation behind each one.
- First payment is issued. Typically actual cash value: the replacement cost minus depreciation and your deductible.
- We build the roof. Tear-off, decking inspection, underlayment, flashing, ventilation, shingles, daily cleanup, permits pulled where the jurisdiction requires them.
- Final documentation goes in and depreciation is released. The held-back amount is paid once the work is complete and invoiced.
ACV, RCV and your deductible
Two terms decide what a storm claim is worth to you. Replacement cost value is what it costs to put the roof back today. Actual cash value is that number minus depreciation for the age and condition of the old roof. On a replacement-cost policy you are paid in two pieces: ACV up front, and the recoverable depreciation after the work is finished and documented. On an actual-cash-value policy the depreciation is simply not paid — which is worth knowing before a storm rather than after.
Your deductible is yours. Any contractor offering to absorb it, rebate it or bury it in an inflated invoice is proposing to defraud your carrier with your name on the paperwork. It is also the clearest available signal that the rest of their work will cut corners too. We will never ask you to do that.
Storm chasers, and how to spot one
Hail brings out-of-state crews into a market within days. Some are competent. Many are gone by fall, along with the workmanship warranty they promised. What to watch for:
- Out-of-area phone numbers and no permanent local office
- A knock at the door within hours of the storm, with pressure to sign the same day
- A contract that authorizes them to negotiate directly with your carrier
- Offers to cover, waive or split your deductible
- Large deposits demanded before any material is delivered
- No verifiable license number, no proof of insurance, no local references
The practical test is simple: ask where their office is, and ask who answers the phone in February. A workmanship warranty is only as durable as the company standing behind it. We have been family-owned and operated through three generations since 1947, with local offices and local crews in every market we serve.
The first 24 hours after a storm
- Stay off the roof. Wet, hail-covered and storm-damaged roofs are genuinely dangerous. Nothing up there needs you tonight.
- Photograph everything from the ground — the yard, gutters, siding, air conditioner, deck, and any hail still on the ground next to a coin for scale.
- Contain the water inside. Buckets, and a small hole punched in a bulging ceiling to let water drain in one controlled place rather than bringing the whole ceiling down.
- Move what matters out from under the leak, and cut power to affected circuits if water is anywhere near fixtures or outlets.
- Call for an inspection and emergency tarping. We answer 24 hours a day, and we photograph the damage before we cover it so the evidence survives the repair.
What our free inspection includes
- A slope-by-slope walk of the roof, with test areas marked and photographed
- Soft metals, siding, windows and other collateral surfaces checked and documented
- Flashing, valleys, pipe boots, vents and decking condition assessed
- Attic and ventilation review where access allows
- Photo documentation you keep, whether or not you file a claim
- A straight answer on whether there is a claim here at all
Storm season across our markets
Spring, roughly March through June, is the heart of hail season across Missouri, Kansas, Illinois and Indiana. Warm, moist air moving north under cold air aloft is exactly what builds large hail, and it is when most roof damage in these markets happens.
Summer shifts the risk toward straight-line wind. Derechos and collapsing thunderstorm outflows can push damaging gusts across entire regions in a single evening, stripping ridge caps and unsealing shingles over a wide area without a single hailstone falling.
Winter brings ice dams. Heat escaping into an under-insulated or under-ventilated attic melts snow on the upper roof; the water refreezes at the cold eave and backs up under the shingles. Ice-dam leaks are a ventilation problem wearing a roofing costume, which is why we look at intake and exhaust on every inspection.
Roof age changes the whole conversation
The same storm produces different outcomes depending on what it lands on. A newer roof with pliable shingles and intact seals can shrug off marginal hail. A fifteen-year-old roof in the same neighborhood may have brittle mats, worn seal strips and prior damage stacked underneath. Age also affects the money: depreciation grows as the roof ages, so the gap between actual cash value and replacement cost widens every year you wait. If your roof is older and a storm has come through, that is the case for getting it looked at now rather than after the next one.
Our nine local markets
Frequently asked questions
- How do I know if my roof has hail damage?
- You usually cannot tell from the ground. Hail bruising is a fractured mat under the granules, not a visible hole, and a bruised shingle often looks normal for years before it splits and leaks. A trained inspection checks the slopes plus soft metals like gutters, vents and AC fins that help date the event. The inspection is free, so there is no reason to guess.
- How long after a storm can I file a claim?
- Policies set their own reporting deadlines, and many are shorter than homeowners expect. Because hail damage is invisible from the ground, roofs are frequently inspected for the first time after the window has already closed. If a storm came through your area, have it looked at now rather than when a stain appears on the ceiling.
- Do you do emergency tarping?
- Yes, 24 hours a day. We stop the water first and photograph the damage before we cover it, because once a roof is tarped and dried in, the evidence for your claim is underneath the tarp.
- What size hail damages a roof?
- Quarter-size hail, about one inch, is commonly where carriers and manufacturers begin expecting functional damage to asphalt shingles. Smaller hail can still damage older, brittle or previously damaged roofs, along with gutters, vents and siding. Wind direction and roof age matter as much as the size of the stone.
- Will filing a storm claim raise my rates?
- Storm claims are weather losses rather than at-fault losses, and carriers generally treat them differently. Rates are set by your carrier and your region, not by us, so ask your agent directly. What we can tell you is what the damage is and what it costs to repair, so you can make that decision with real information.
- Do I have to pay my deductible?
- Yes. The deductible is your share of the loss under your policy. Any contractor offering to waive it, absorb it or hide it in an inflated invoice is asking you to participate in insurance fraud, and that is a reason to send them away.
- Can you work with my insurance company?
- We document the damage thoroughly and meet your adjuster on site so everyone is looking at the same evidence. We are roofers, not public adjusters, so the claim itself stays between you and your carrier. In practice, a well-documented inspection is what keeps items from being missed in the scope.
- What does a storm-damage inspection cost?
- Nothing. We inspect, photograph and document the roof at no charge, and you keep the documentation whether or not you file a claim. If your roof is fine, we will tell you that.